The stack of bills on your kitchen counter feels heavier with each passing month, not because you’re spending more, but because your minimum payments are barely touching the principal. You’ve committed to paying down debt, but now, with interest rates climbing, it feels like you’re running on a treadmill that’s speeding up. I’ve been there, watching my hard-earned extra payments get swallowed by ever-increasing interest charges. It’s demoralizing to feel like you’re working harder just to stay in the same place.
This isn’t just a hypothetical scenario; it’s the reality for millions of Americans facing variable interest rates on credit cards, personal loans, and even some older mortgages. When the Federal Reserve raises its benchmark rate, your creditors quickly follow suit. What was once a manageable 16% APR on your credit card can quickly become 20%, 22%, or even higher, turning your debt payoff plan into a frustrating uphill battle. The mistake I see most often is people simply continuing with their old plan, hoping the rates will eventually stabilize or drop. But hope isn’t a strategy, especially when every percentage point increase means hundreds, if not thousands, of extra dollars paid in interest over the life of your debt. What changed everything for me was a proactive, aggressive pivot in my strategy – focusing not just on paying more, but on paying smarter.
Key Takeaways
- Prioritize high-interest, variable-rate debts like credit cards for accelerated payoff over fixed-rate loans.
- Transfer balances to 0% APR cards or seek low-interest personal loans to create a temporary shield against rising rates.
- Aggressively cut discretionary spending and reallocate every spare dollar to the highest-interest debt.
- Negotiate directly with creditors for lower interest rates or hardship plans before debt becomes unmanageable.
Rethink Your Debt Prioritization Strategy Immediately
When interest rates are stable or falling, the choice between the debt snowball (paying off smallest balances first) and debt avalanche (paying off highest interest rates first) methods can come down to personal preference for psychological wins versus pure mathematical savings. However, with rising interest rates, the debt avalanche method isn’t just mathematically superior; it becomes a critical defense against escalating costs. Your priority must shift immediately to attacking the debt that is costing you the most and is most susceptible to rate hikes. This almost always means high-APR credit card debt with variable rates.
In my experience, many people get emotionally attached to clearing small debts first because it feels good to see a balance go to zero. While that psychological boost is real, it’s a luxury you can’t afford when interest rates are actively increasing. Imagine you have a $500 balance at 15% APR and a $5,000 balance at 22% APR. If rates jump another 2%, that $5,000 balance is now costing you significantly more. Every month you delay aggressively paying down that 24% APR credit card, you’re losing money that could have gone towards principal. I once focused on a small, $300 department store card when I had a much larger balance on a major credit card. The small win felt good for about a week, but the relentless march of interest on the larger debt quickly overshadowed any sense of accomplishment. I realized I was essentially leaving money on the table, allowing the most expensive debt to grow while I celebrated minor victories.
Here’s how to pivot: List all your debts, their current balances, interest rates, and whether the rate is fixed or variable. Circle every variable-rate debt, especially those with high APRs. These are your prime targets. If you have any fixed-rate loans with rates below 7-8% and high-interest credit card debt above 18%, pause extra payments on the fixed-rate loans and redirect everything to the variable, high-APR debt. This isn’t about ignoring other debts; it’s about strategically allocating your resources to minimize the damage from rising rates.
Utilize 0% APR Balance Transfer Cards, but With Extreme Caution
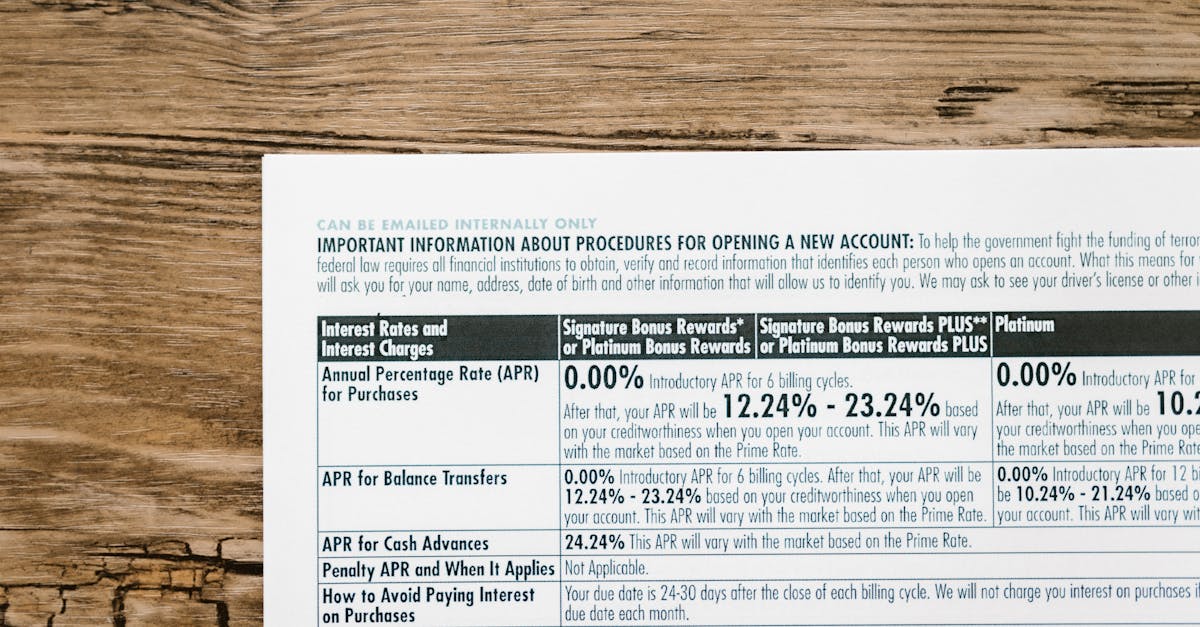
One of the most effective ways to temporarily shield yourself from rising interest rates is to transfer high-interest credit card balances to a new card offering a 0% introductory APR. These offers typically last for 12 to 21 months. This strategy isn’t a magic bullet; it’s a time-limited opportunity to aggressively pay down principal without any interest charges eating into your payments. But the ‘extreme caution’ part is critical.
When I first explored a balance transfer, I was tempted to see it as a fresh start, a chance to ‘reset.’ That mindset is dangerous. Many people make the mistake of transferring a balance, making only minimum payments, and then finding themselves with an even larger balance at a high interest rate once the promotional period ends. They might even rack up new debt on the old, emptied card. This is a recipe for disaster. What worked for me was treating the 0% APR period like a sprint. I transferred a $7,000 balance from a 20% APR card to a new card with 15 months at 0% APR, plus a 3% transfer fee. My original minimum payment was about $140, with most of it going to interest. With the 0% card, my payment became $466 per month ($7,000 / 15 months) to pay it off completely before the intro rate expired. This felt daunting, but knowing every dollar went to principal was incredibly motivating. I then cut up the old card and put the new one in a safe place, vowing not to use it for new purchases.
Before you apply for a balance transfer card, calculate exactly how much you need to pay each month to clear the balance before the 0% period ends. Factor in any balance transfer fees, which are typically 3-5% of the transferred amount. Only transfer what you can realistically pay off. If you can’t pay it off, you might still save money on interest during the promotional period, but you must be prepared for the original (or even higher) interest rate to kick in on any remaining balance.
Explore Debt Consolidation Loans for Fixed, Lower Rates
For those with significant high-interest debt across multiple credit cards, a debt consolidation loan can be a powerful tool, especially in a rising interest rate environment. The goal here is to replace several variable-rate, high-APR debts with a single fixed-rate loan at a lower overall interest rate. This locks in your rate and provides predictable monthly payments, making it easier to budget and track progress.
However, this strategy comes with its own set of traps. The biggest one is not addressing the root cause of the debt. I’ve seen friends consolidate their debt, only to run up their credit cards again because they didn’t fix their spending habits. It’s like putting a band-aid on a gushing wound. When I consolidated my credit card debt years ago, I specifically looked for a loan that offered a fixed rate significantly lower than my average credit card APR, which was around 19%. I found a personal loan for $12,000 at 9.5% for 48 months. This reduced my monthly payments from a chaotic $400+ across several cards to a predictable $300 for the loan, all while saving me thousands in interest. But before I even applied, I sat down and created a strict budget, committing to stop using credit cards for anything I couldn’t pay off immediately.
When considering a consolidation loan, compare the APR of the new loan to the weighted average APR of your existing debts. Make sure the new loan truly offers a lower overall cost. Be wary of loans with extremely long repayment terms that might reduce your monthly payment but could end up costing you more in total interest. The best candidates for debt consolidation loans are those with good credit scores, as they qualify for the most favorable rates. If your credit score isn’t strong, you might find that the interest rates offered on consolidation loans aren’t significantly better than your current credit card rates, making the effort counterproductive. Always prioritize securing a fixed rate to protect against future interest rate increases.
Aggressively Cut Discretionary Spending and Redirect Funds
When interest rates are climbing, every dollar you redirect towards debt payoff works harder for you by preventing more interest from accruing. This means it’s time to examine your budget with a magnifying glass and ruthlessly cut discretionary spending. This isn’t about depriving yourself indefinitely, but about making temporary sacrifices to protect your financial future from the compounding effect of rising rates.
I’m not talking about minor tweaks here. I mean a deep dive into where every non-essential dollar goes. For me, this looked like a ‘spending fast’ for several months. I cut out all restaurant meals, stopped my daily fancy coffee habit, paused my streaming services (I re-evaluated them later), and even minimized my grocery bill by planning meals meticulously and cooking everything from scratch. This wasn’t easy, and I certainly felt the pinch. But when I saw how much extra I could put towards my highest-interest debt – often an additional $300 to $500 per month – the sacrifice felt worthwhile. That extra cash wasn’t just reducing my debt; it was preventing it from growing faster due to the new rate hikes.
Start by tracking every single expense for a week or two. You’ll likely find subscriptions you forgot about, impulse purchases that add up, or habits that aren’t truly bringing you joy. Create a temporary ‘bare-bones’ budget for one or two months. Challenge yourself to see how much you can truly free up. Think beyond simply cutting: can you carpool more, walk or bike instead of driving, cancel unused gym memberships, or even temporarily downgrade your phone plan? The goal is to funnel as much money as possible into those vulnerable high-interest debts. This focused intensity won’t last forever, but it’s a powerful way to gain momentum and minimize the impact of external economic forces on your personal finances.
Communicate Directly with Your Creditors
Many people are surprised to learn that creditors are often willing to work with you, especially if you proactively reach out before you fall behind on payments. In a rising interest rate environment, this becomes an even more valuable strategy. Don’t hesitate to call your credit card companies or loan providers to negotiate for a lower interest rate or explore hardship programs. They would rather receive consistent payments at a slightly lower rate than have you default entirely.
I remember feeling incredibly nervous the first time I called my credit card company. I envisioned a rigid, unhelpful conversation. What I found was a representative who was surprisingly understanding. I explained my commitment to paying off the debt and my concern about the rising interest rates making it difficult to progress. I politely asked if there were any programs or options available to reduce my APR. To my surprise, after reviewing my account, they offered to lower my rate by two percentage points for six months. It wasn’t a massive drop, but it saved me enough to feel like my extra payments were making a real difference. This experience taught me that simply asking can often yield positive results.
When you call, be polite but firm about your intent to pay off the debt. Highlight your good payment history, if you have one. Ask directly for a lower interest rate. If that’s not possible, inquire about hardship programs, even if you’re not officially in hardship yet. Some creditors offer temporary payment reductions or even principal deferment. The key is to be transparent about your situation and your goals. Be persistent; if the first representative can’t help, thank them and call back another time. You might get a different outcome. This proactive communication can buy you precious time and reduce the cost of your debt while you implement other payoff strategies.
Frequently Asked Questions
How quickly do rising interest rates impact my existing debt?
For variable-rate debts like credit cards and some personal loans, interest rate increases can impact your debt almost immediately. Creditors typically adjust your APR shortly after the Federal Reserve announces a rate hike, often within one or two billing cycles. This means your minimum payment can increase, and a larger portion of your payment will go towards interest rather than principal, unless you’re paying significantly more than the minimum.
Should I prioritize paying off my mortgage if interest rates are rising?
Generally, no, not if you have high-interest, variable-rate debts like credit cards. Most mortgages have fixed interest rates, especially if you’ve recently refinanced or taken out a new loan. Even if you have an adjustable-rate mortgage (ARM), its rate adjustments are usually capped annually and over the loan’s lifetime. High-APR credit card debt, often with rates above 18-20%, will cost you far more in the short and medium term than a mortgage at 5-7%, even if that mortgage rate creeps up slightly. Focus your extra payments on the most expensive, most volatile debts first.
Can rising interest rates affect my student loans?
Yes, but it depends on the type of student loan. Federal student loans typically have fixed interest rates for the life of the loan, so they are not directly affected by rising rates after disbursement. Private student loans, however, can have variable interest rates. If you have private student loans with variable rates, they will likely see rate increases in line with broader market trends, leading to higher monthly payments or a longer repayment period.
Is taking out a new loan to consolidate debt a good idea when rates are rising?
It can be, but it requires careful evaluation. The primary benefit is to secure a fixed interest rate lower than your current average variable rates, thereby shielding you from further increases and providing payment predictability. However, ensure the new loan’s APR is truly lower, and be disciplined about not accumulating new debt on the old, emptied credit lines. If your credit score is poor, the consolidation loan offered might not have an attractive enough rate to make it worthwhile.
How can I make extra money quickly to accelerate debt payoff?
Consider temporary side hustles or selling unused items. Deliver groceries, walk dogs, offer freelance services, or sell clothes and electronics you no longer need. Even a few hundred extra dollars a month can make a significant difference in tackling high-interest debt, especially when rates are rising. Think of it as a temporary surge of income to gain critical momentum against escalating interest charges.
Conclusion
Rising interest rates are a harsh reality that can make debt payoff feel like an insurmountable challenge. But by understanding how these rate hikes impact your specific debts and adopting a proactive, aggressive strategy, you can regain control. Prioritize your highest-interest, variable debts, strategically use balance transfers and consolidation loans, ruthlessly cut discretionary spending, and don’t be afraid to negotiate with your creditors. This isn’t just about paying off debt; it’s about protecting your financial future from forces outside your control. Start by reviewing your debts today and making a plan to attack the most vulnerable ones first. Your future self will thank you for acting decisively.